We Handle the Claim, Not Just the Roof

Roofing Insurance Claims Across Indiana, Tennessee and Kentucky

BBB Icon2
5 Star and A+ Rating

Google, Facebook & BBB

Request a Free Quote!

Google Rating Logo
GAF certified logo
BBB Logo
Facebook Rating Logo
Shingle Master Logo
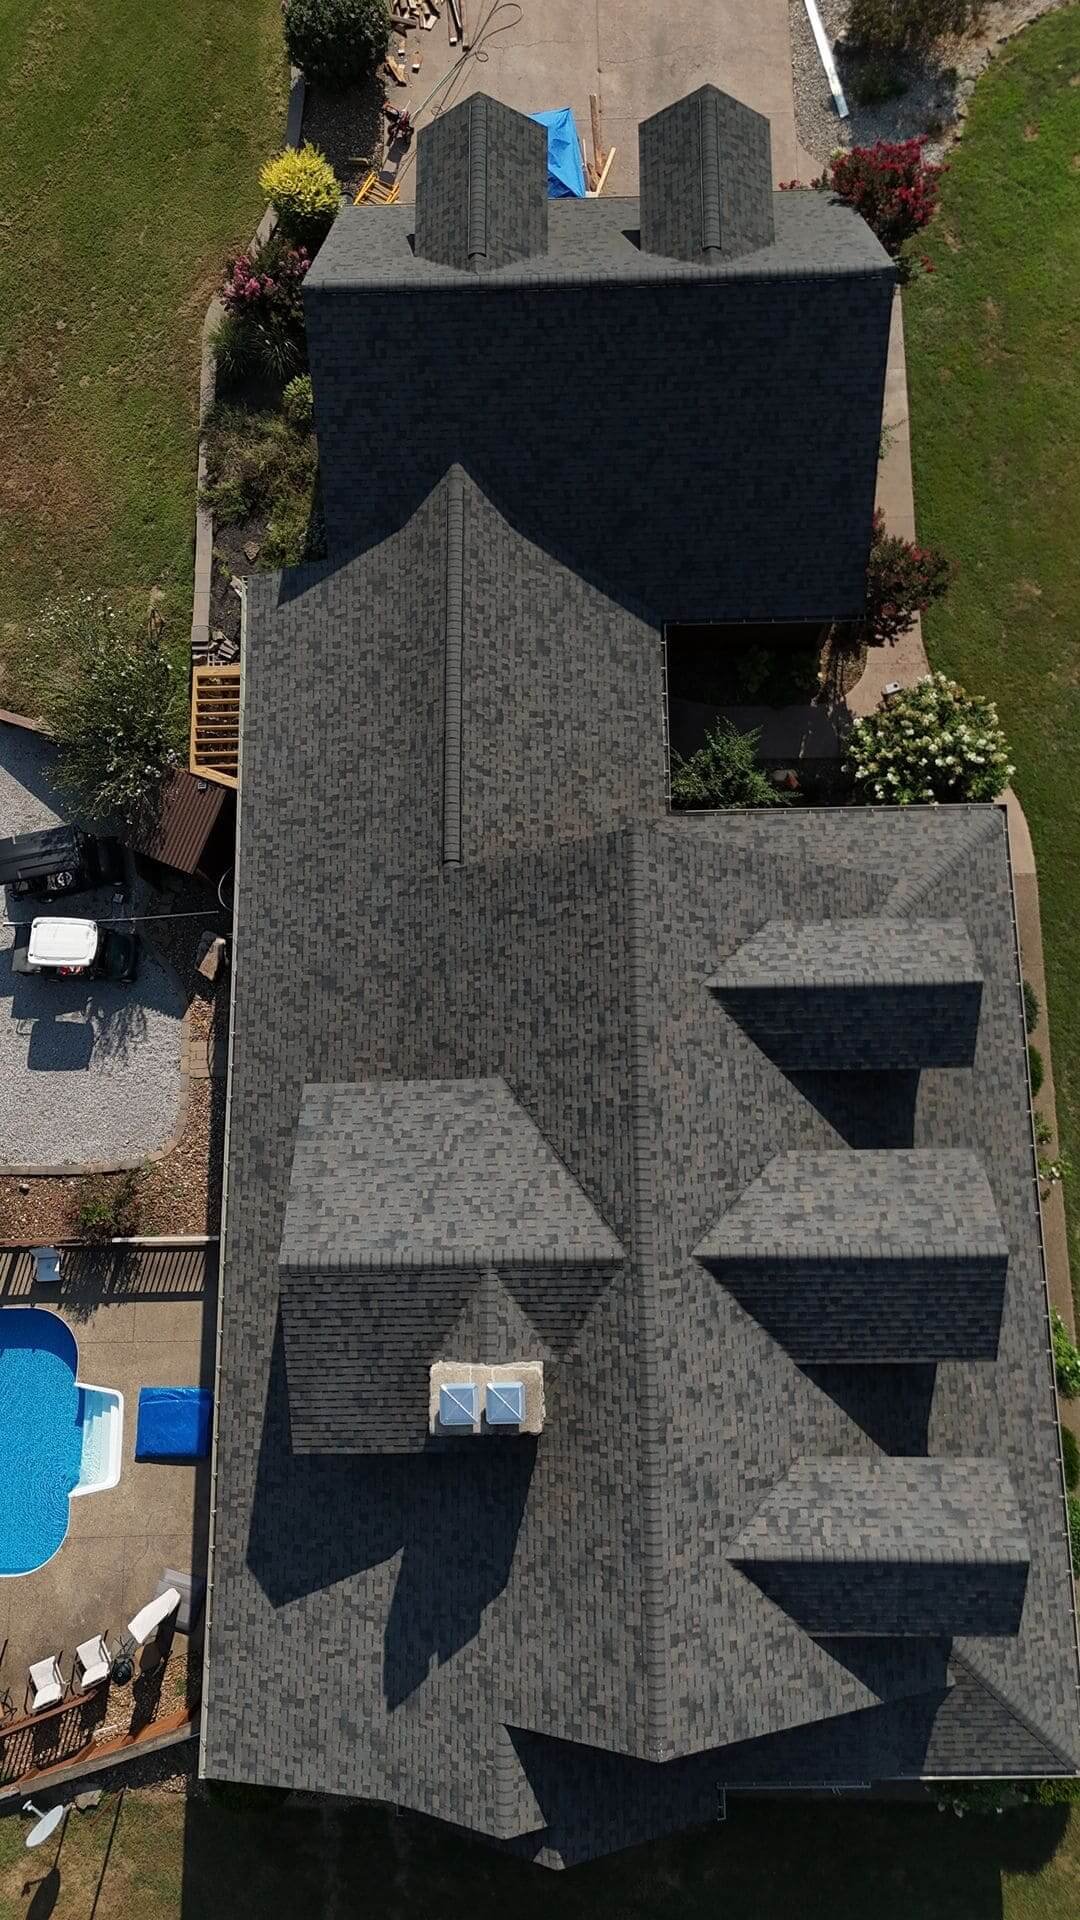
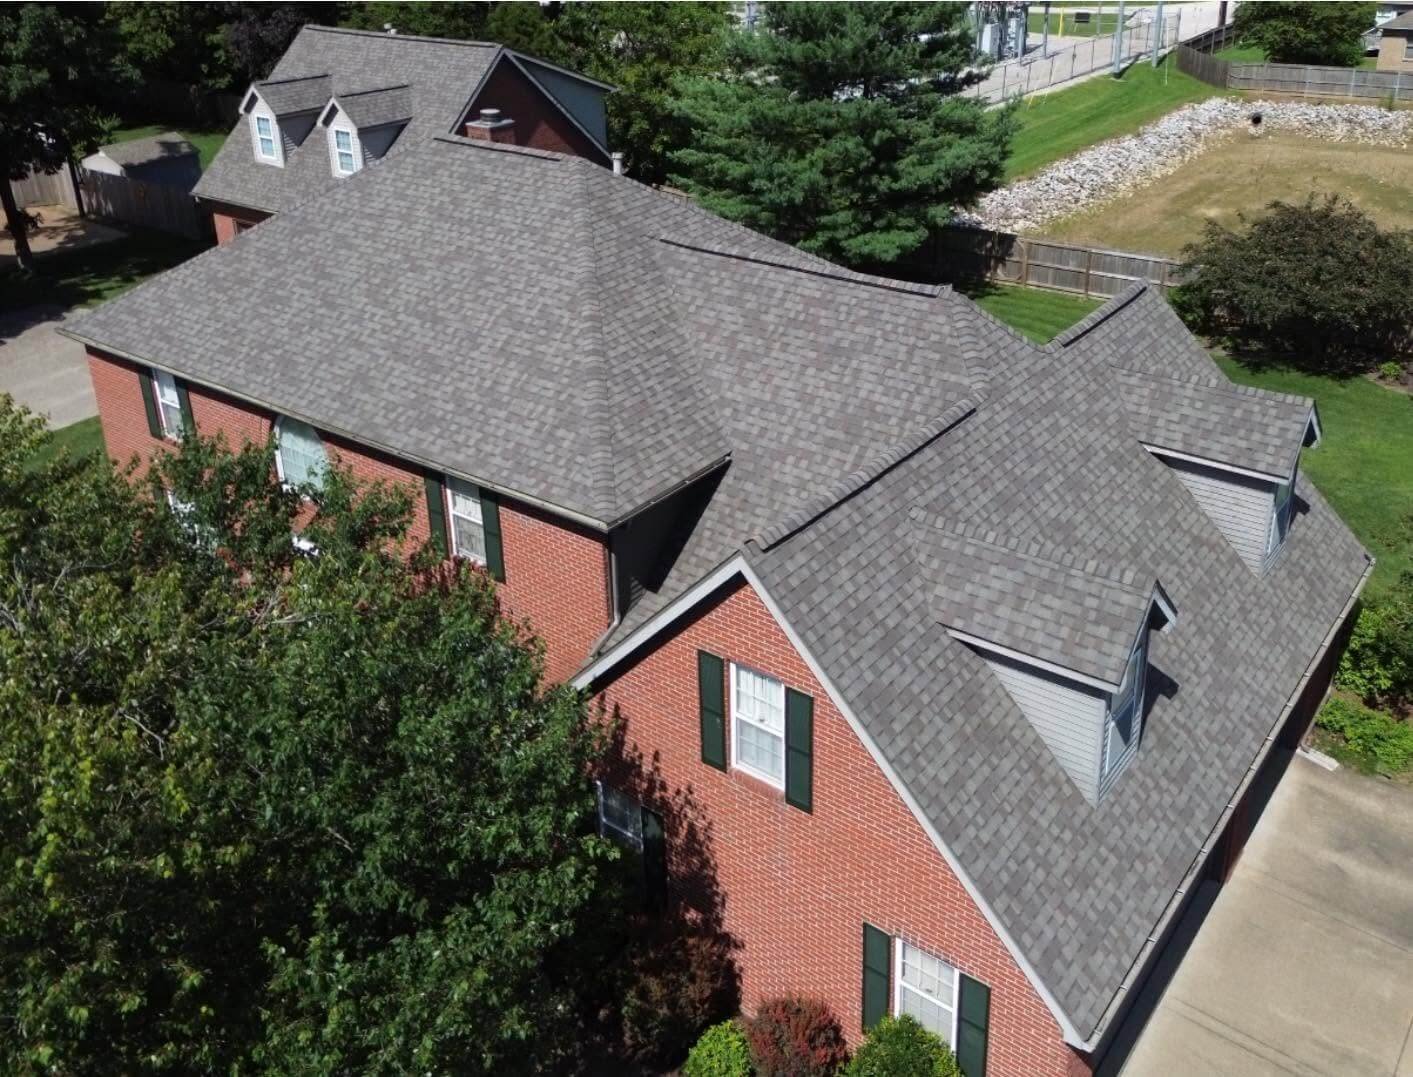
Roof damage documentation for an insurance claim
Why Claims Go Wrong

Most Denied Claims Were Never Properly Documented

When a legitimate roof claim gets denied or underpaid, the damage was almost always real. What failed was the evidence. Hail damage on an asphalt roof has to be identified slope by slope, photographed clearly, and presented in a form an adjuster can act on. A one-page report with three photos gives an insurer every reason to pay less than the claim is worth.

It is not a fair fight either. The adjuster does this every day and knows exactly what the policy does and does not cover. The homeowner is doing it for the first time, usually while dealing with a damaged house, and is expected to argue the technical case for why bruising on a north slope qualifies as storm damage.

That is the gap we close. We inspect the full roof, document every affected area to the standard the insurer requires, and present the claim properly from the start. Getting it right first time is far easier than appealing a decision afterwards.

The inspection is free and there is no obligation. If we do not think you have a claim, we will tell you.

What We Actually Do

From Inspection to Final Walkthrough

We start with a full documented inspection, photographed and recorded slope by slope, with the damage identified and described in the terms the policy uses. You get a copy of everything.

We then deal with your adjuster directly, including meeting them on site where that helps. Having someone who understands roofs present when the adjuster inspects frequently changes the outcome, simply because the damage gets pointed out rather than missed.

Once the claim is settled we carry out the work, and the scope matches what was approved. If you choose upgrades beyond what the policy covers, we set out clearly what the insurer is paying and what you are, before anything starts. Financing can cover your deductible or any upgrade if needed.

We do not inflate claims, and we will not tell you a sound roof is damaged. That is insurance fraud and it is also a very short-term way to run a business. What we do is make sure real damage gets paid for properly.
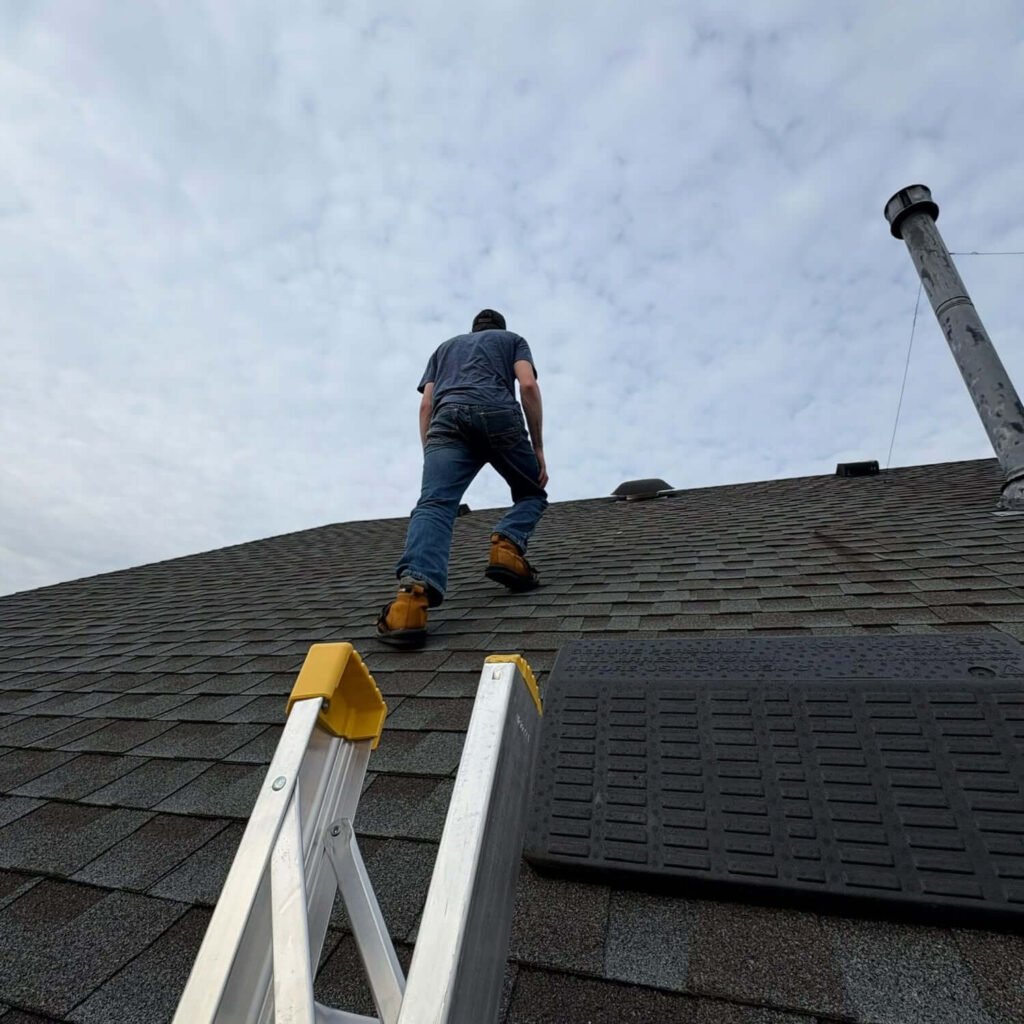
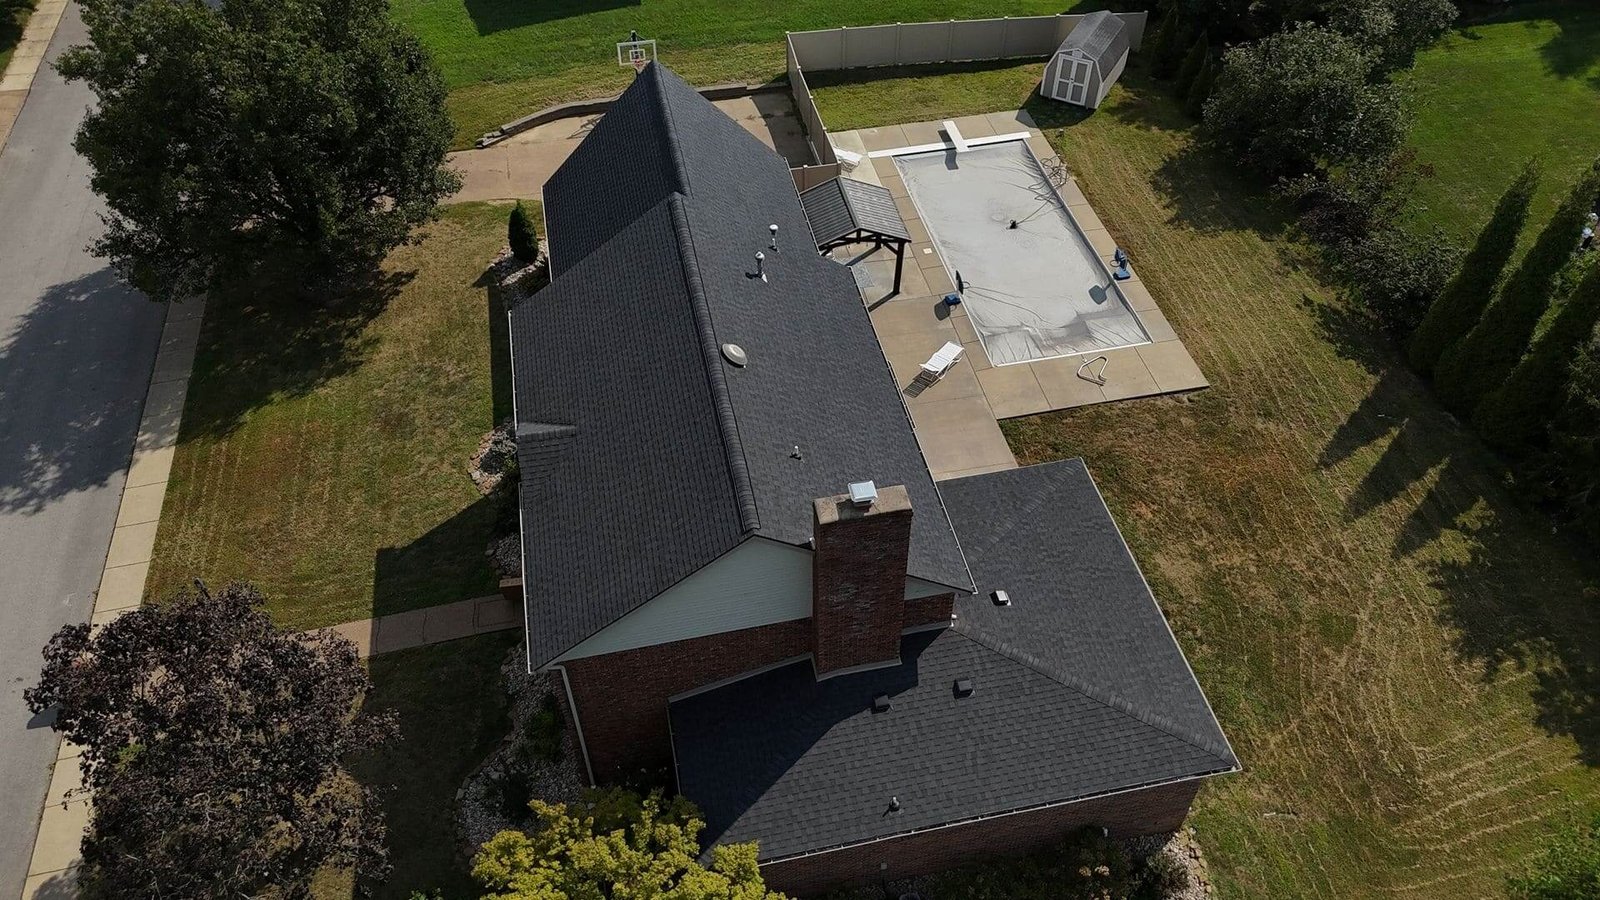
Insurance claim roof replacement completed
Red Angle Image

why choose us

five Reasons Homeowners Deal Us In

Winning Hand Roofing & Restoration About Image2
Built on Repeat Customers


Most of our work comes from people who have used us before or were sent by someone who did. That only happens if you do the job right the first time.

When a storm hits, we don’t wait for business hours. Call any time, day or night, and we’ll get someone out to tarp, assess, and stop further damage before it gets worse.
We work directly with your adjuster and document everything with photos and a detailed report. Most homeowners never have to chase down paperwork or fight for what they’re owed.
We carry full licensing and insurance everywhere we work, and our crews are certified to install the systems we recommend. That means proper installation and warranties that actually hold up.

Every roof we install is backed by a workmanship warranty from us and a manufacturer warranty on materials. If something goes wrong that shouldn’t, we come back and make it right.
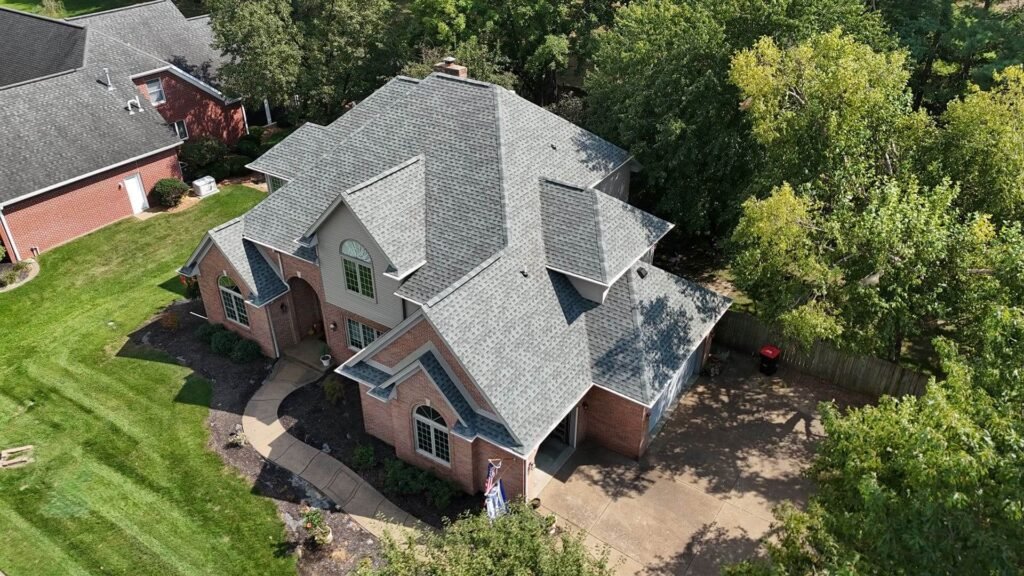
Past work

The Winning Hand Team In Action

Red Angle Image
Have Questions? We Have Answers.

Common Questions About Roof Insurance Claims

Will my insurance cover a new roof?
If the damage came from a covered event such as hail or wind, often yes. Age-related wear and tear is not covered by any policy. The outcome usually depends on how well the damage was documented.
Most commonly because the documentation was too thin to establish that storm damage occurred, or because the damage was classified as wear rather than an event. Both are worth challenging with a proper inspection.
Yes. We document the damage to the standard required and handle the adjuster conversation ourselves, including meeting them on site where it helps.
That depends on your insurer and policy, and it is worth asking them directly. Weather-related claims are generally treated differently from at-fault claims, but we cannot advise on your specific policy.
There is usually a time limit from the date of the storm, and it varies by policy. Do not wait for a leak, because hail damage frequently does not leak until after the window has closed.
Bring it to us. We will inspect independently and tell you whether the report reflects what is actually on your roof. Second opinions change outcomes more often than people expect.
No. Waiving or absorbing a deductible is insurance fraud and we will not do it. Financing is available from $99 a month if paying the deductible up front is the obstacle.
Yes, at no cost and no obligation, with full written documentation you keep regardless of what you decide.

Get a FREE Quote Today